
April 1, 2021Virtual seminar
Equilibrium Asset Pricing with Liquidity Risk
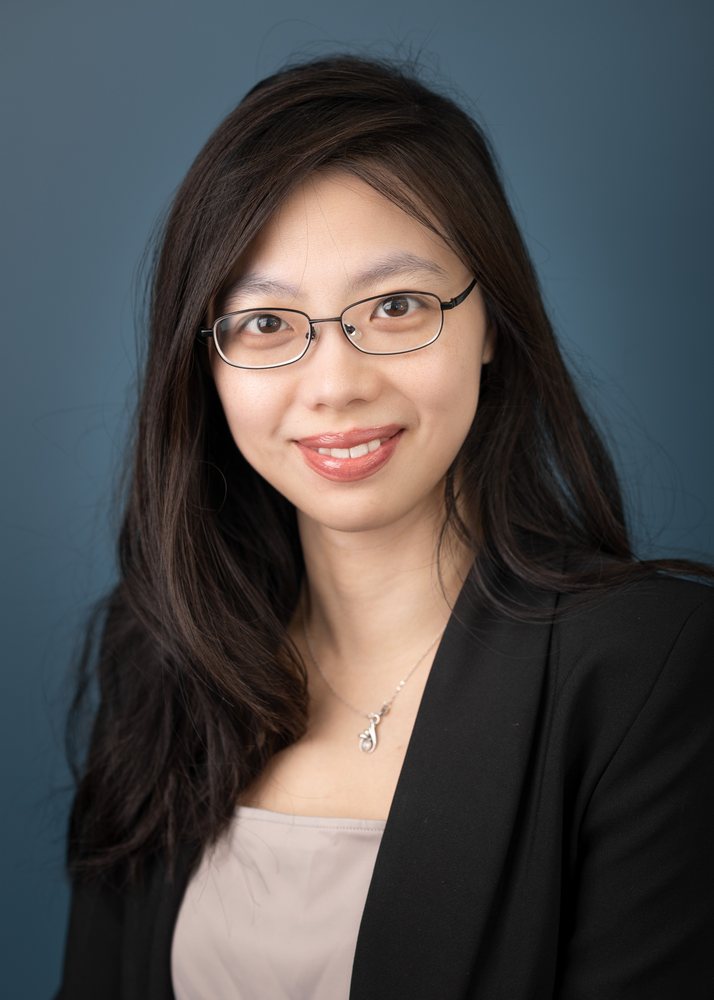
Xiaofei ShiDepartment of Statistics, Columbia University
Abstract
In a risk-sharing economy we study how the price dynamics of an asset depends on its “liquidity”. An equilibrium is achieved through a system of coupled forward-backward SDEs, whose solution turns out to be amenable to an asymptotic analysis for the practically relevant regime of large liquidity. We also discuss how to leverage deep-learning techniques to obtain numerical solutions, and compare them with our asymptotic approximations.
Watch recording ↗About the speaker
No bio is available for this talk.