
An alpha-potential game framework for dynamic N-player games
Abstract
Game theory has a long history, yet identifying Nash equilibria in dynamic non-cooperative games remains a fundamental challenge with significant computational and conceptual complexity. Over the past decade, mean field game theory has emerged as a pivotal framework, offering important theoretical insights and computational advances for the analysis of large-scale stochastic games. However, mean field games require homogeneity and weak interactions among players and focus only on the limiting behavior when the number of players goes to infinity. In this talk, we present a new paradigm for dynamic N-player games, called alpha-potential games, where the change of a player's objective function resulting from a unilateral deviation of her strategy is equal to the change of an alpha-potential function up to an error alpha. Within this framework, the problem of computing approximate Nash equilibria reduces to a stochastic control problem for the alpha-potential function, significantly simplifying both analysis and computation. The parameter alpha also reveals important structural properties of the game, such as the population size, the intensity of player interactions, and the degree of heterogeneity across players. We will discuss through simple examples some recent theoretical and algorithmic developments, along with a few open problems for this new game framework.
Watch recording ↗About the speaker
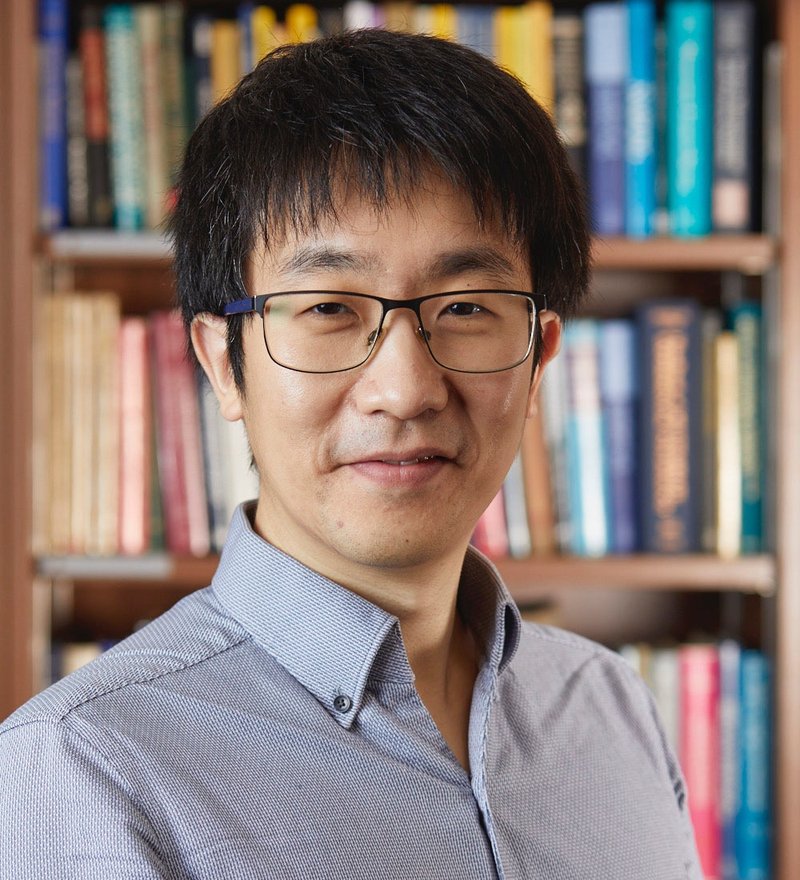
Yufei Zhang is an Associate Professor in Mathematical Finance and Machine Learning in the Department of Mathematics at Imperial College London, where he also serves as Co-Director of the MSc in Mathematics and Finance program. Before joining Imperial, he was an Assistant Professor in the Department of Statistics at the London School of Economics and Political Science. He earned his PhD in Mathematics from the University of Oxford in 2021. Yufei was awarded the J.P. MorganChase Faculty Research Award in 2025 for his work on the mathematics of artificial intelligence. Yufei's research lies at the intersection of stochastic control, game theory, machine learning, and mathematical finance, with a particular emphasis on developing theoretical foundations and algorithmic frameworks for complex decision-making in dynamic and uncertain environments.