
Boundary attainment conditions for stochastic Volterra equations
Abstract
In this presentation, I will discuss boundary attainment conditions for one-dimensional stochastic Volterra equations (SVEs) of convolution type. In the first part of the talk, I will present an Osgood-type test for explosion to infinity of SVEs driven by additive noise, featuring kernels from a family that includes the fractional kernel. I will also investigate stability results for explosion times with respect to the kernels, including the case of an Euler-Maruyama approximation scheme. In the second part, I will present a Feller-type test that establishes, on a general open interval of the real line, necessary and sufficient conditions for boundary attainment of solutions to SVEs with possibly multiplicative noise. Here, I will consider dynamics governed by nonsingular kernels, which preserve the semimartingale property of the processes while introducing memory effects through a path-dependent drift. I will also show an application of these results to the Volterra square-root diffusion. The talk is based on joint works with Alessandro Bondi.
Watch recording ↗About the speaker
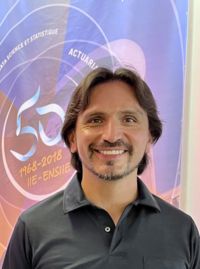
Sergio Pulido is an Associate Professor (Maître de conférences HDR) at the École Nationale Supérieure d'Informatique pour l'Industrie et l'Entreprise (ensIIE) and a permanent member of the Laboratoire de Mathématiques et Modélisation d'Évry (LaMME), a joint research unit of the Centre National de la Recherche Scientifique (CNRS), Université Évry Paris-Saclay, and the ensIIE. He currently serves as Head of the International Relations Office at the ensIIE and co-manages the M1 in Applied Mathematics (Évry site) at Université Paris-Saclay. He is also an Associate Researcher in the Mathematical Finance group at the Centre de Mathématiques Appliquées (CMAP) of École Polytechnique. Before joining ensIIE, he was a Postdoctoral Researcher at the Swissquote Chair in Quantitative Finance at the École Polytechnique Fédérale de Lausanne (EPFL), and a Postdoctoral Associate in Applied Probability and Mathematical Finance at Carnegie Mellon University. He received a PhD in Mathematics from Cornell University, an M.S. in Mathematics from Universidad de los Andes, and a B.S. in Mathematics from Universidad Nacional de Colombia. Sergio Pulido's recent research focuses on stochastic models with rough trajectories and their applications in finance. From a more theoretical perspective, he has studied stochastic processes solving stochastic convolution equations, namely Stochastic Volterra Equations (SVEs).